Why Auto Insurance Rates Vary From Driver to Driver
A starter outline about common rating factors.
Have you ever compared your car insurance bill with a friend, neighbor, or family member and wondered why you are paying different amounts?
Maybe you both drive similar cars. Maybe you live only a few streets apart. You may even use the same insurance company.
Still, one of you can pay noticeably more than the other.
That happens because auto insurance is not priced with one fixed rate for everyone. Insurance companies look at a combination of details to estimate the risk connected with each driver and policy.
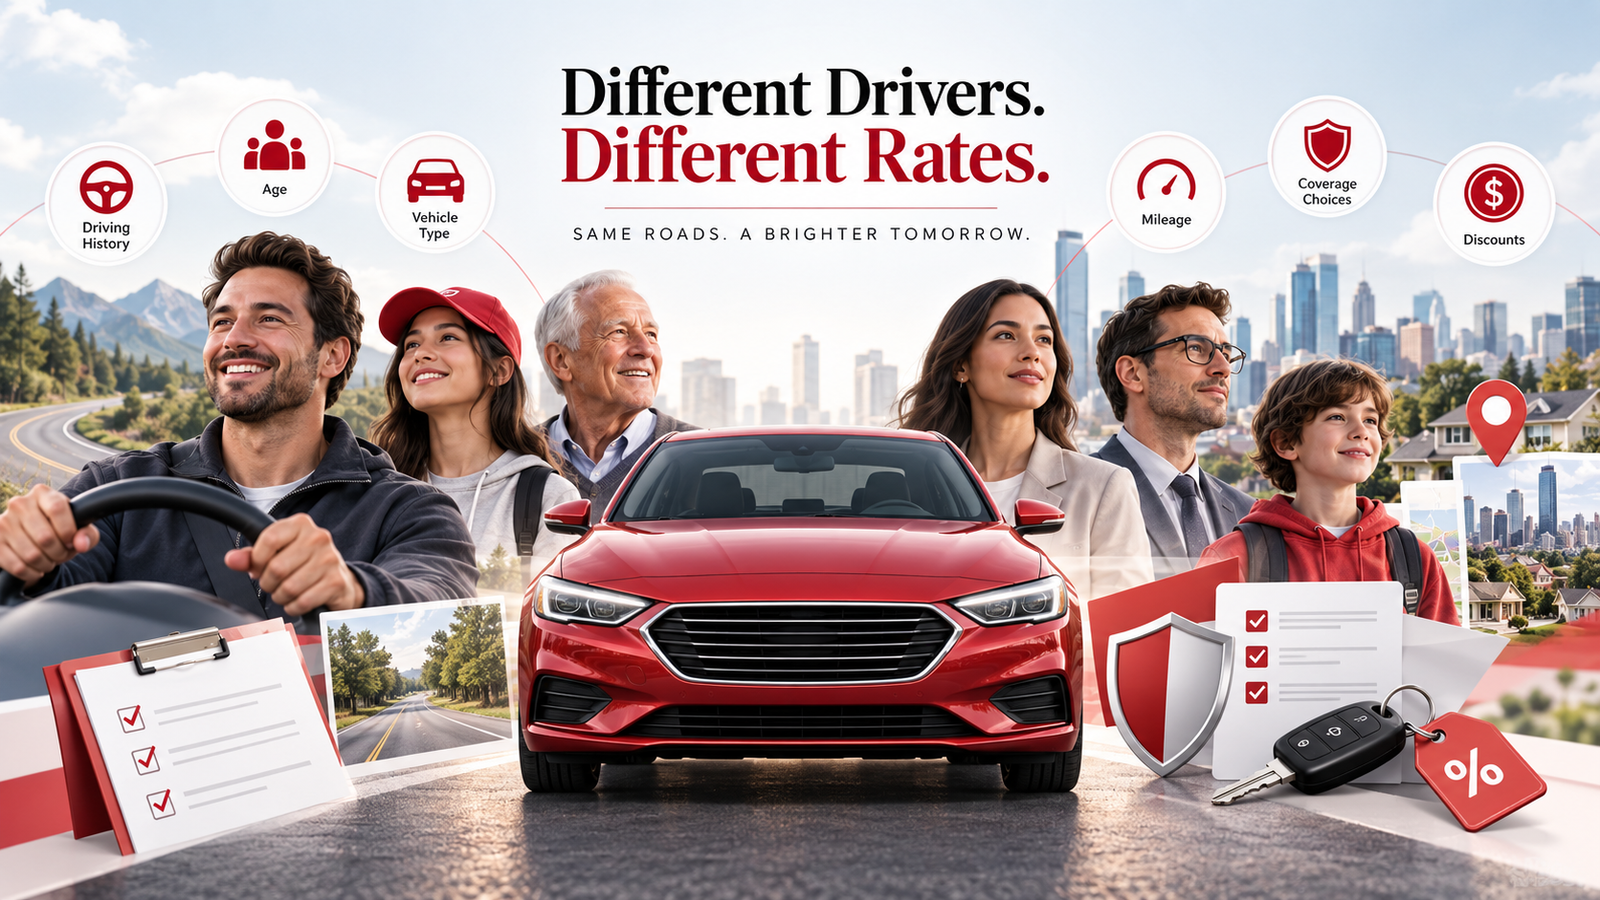
Your driving history, age, experience, vehicle, location, annual mileage, coverage choices, deductible, and available discounts can all play a part.
This is also why searching for the cheapest company based only on someone else’s experience can be misleading. The company that is inexpensive for your friend may not be inexpensive for you.
Understanding why auto insurance rates vary from driver to driver can help you compare policies more intelligently and avoid paying for coverage without understanding what is affecting the price.
Auto Insurance Is Priced Around the Driver's Risk Profile
Insurance companies try to estimate how likely a policy is to result in a claim and how expensive that claim could be.
To do that, they build a risk profile using information about the driver, vehicle, location, and policy.
This does not mean that one individual factor automatically determines your price.
Your premium is normally the result of several factors working together.
For example, a driver may have an excellent driving record but own an expensive vehicle that costs a lot to repair. Another driver may own an inexpensive car but live in an area with heavier traffic and more insurance claims.
Both drivers can end up with different premiums for completely different reasons.
That is why insurance pricing should be viewed as a combination of factors rather than one simple calculation.
Driving History Can Make a Big Difference
A clean driving history can help show an insurer that you have not recently been involved in certain accidents or serious traffic violations.
On the other hand, recent incidents may affect how an insurer evaluates your risk.
These can include:
- At-fault accidents
- Speeding tickets
- Reckless driving violations
- Other moving violations
- Certain insurance claims
But even here, there is no universal rule that every accident or ticket increases insurance by the same amount.
A minor violation may be treated differently from a serious violation.
A recent accident may be viewed differently from one that happened years ago.
Your previous record can also matter.
Someone with a long clean history before one incident may have a different insurance profile from someone with several recent incidents.
This is one reason two drivers who appear similar on the surface can still receive very different quotes.
Age and Driving Experience Can Affect Insurance Rates
Age and driving experience are closely connected, especially for newer drivers.
A driver who received a license recently does not have the same amount of road experience as someone who has been driving for 20 years.
Young drivers may therefore see higher quotes, particularly during their first years behind the wheel.
But age alone does not determine the final price.
A young driver with a clean record, a sensible vehicle, good student eligibility, and a family policy may have a completely different rate from another driver of the same age.
If you are researching this specifically for a younger driver, our guide on Best Car Insurance for Young Drivers can help you compare age-related insurance options more closely.
Older drivers can also have different insurance needs.
Mileage may fall after retirement, driving habits may change, and mature-driver discounts may become relevant.
For older motorists, the Best Car Insurance for Seniors guide can be a useful next step.
The important point is simple: age matters, but it should never be looked at by itself.
The Car You Drive Can Change Your Premium
Your vehicle can have a major effect on what you pay.
Two drivers with almost identical personal profiles can receive different prices simply because they insure different vehicles.
Insurance companies may consider things such as:
- Vehicle value
- Repair costs
- Replacement parts
- Safety equipment
- Theft risk
- Engine performance
- Claim history associated with the vehicle
- Cost of collision and comprehensive claims
An expensive vehicle may cost more to repair after an accident.
Some vehicles contain advanced cameras, sensors, lights, or electronic systems that can make even a relatively small repair expensive.
High-performance cars can also create a different insurance profile from standard family vehicles.
This is why it is smart to check insurance costs before buying a vehicle rather than waiting until after the purchase.
The cheapest car to buy is not always the cheapest car to insure.
Annual Mileage and How You Use the Car Matter
Think about two drivers.
The first works from home and drives about 4,000 miles per year.
The second commutes long distances every day and drives 20,000 miles per year.
Even if they are the same age and drive similar vehicles, their insurance profiles are not identical.
How much you drive can matter because more time on the road generally means more exposure to situations where an accident could occur.
How the vehicle is used can matter as well.
A car used occasionally for personal trips may be viewed differently from a car used for a long daily commute.
This is why you should provide realistic mileage when requesting insurance quotes.
Do not automatically use an old mileage estimate if your lifestyle has changed.
For example, someone who recently started working from home or retired may now drive considerably less than before.
Where You Live Can Affect What You Pay
Location is another major reason auto insurance rates vary from driver to driver.
A driver living in a quiet rural area may face a different insurance environment from someone living in the center of a busy city.
Insurers can look at local conditions connected with claims and losses.
These may include:
- Traffic volume
- Accident frequency
- Vehicle theft
- Vandalism
- Weather risks
- Repair costs
- Local claim activity
This is why two people with similar driving records can still pay different amounts simply because they live in different places.
Rates can vary between states, but they can also vary inside the same state.
A driver in one city may receive a different quote from a similar driver living elsewhere.
This is also why location is one of the first inputs in many of our car insurance calculators.
State Insurance Rules Are Not the Same Everywhere
Car insurance is heavily influenced by state rules.
Minimum required coverage is not identical throughout the United States.
Some states have different insurance systems, required protections, or restrictions affecting the way policies are priced.
An insurer may also operate differently from state to state.
A discount available in one state may not be available in another.
A company that is highly competitive in one state may be much less competitive elsewhere.
That is why national “cheapest company” lists should always be treated as a starting point rather than a personalized answer.
Our Top 10 Cheapest Car Insurance Companies tool is designed around this problem by separating national comparisons from state and city-level comparisons.
Your Coverage Choices Directly Affect the Price
Not every insurance policy provides the same amount of protection.
One driver may choose only the coverage required by their state.
Another may choose higher liability limits, collision, comprehensive, uninsured motorist protection, rental reimbursement, and roadside assistance.
Naturally, those policies should not be expected to cost the same.
Common coverage choices that can affect price include:
- Bodily injury liability
- Property damage liability
- Collision coverage
- Comprehensive coverage
- Uninsured motorist coverage
- Underinsured motorist coverage
- Medical-related coverage where applicable
- Rental reimbursement
- Roadside assistance
If you are unsure what these protections actually do, read What Does Auto Insurance Cover?
Understanding the coverage first makes it much easier to compare prices correctly.
Your Deductible Can Change the Premium
A deductible is the amount you may have to pay yourself before certain insurance coverage pays toward a covered loss.
For example, one driver might choose a $500 deductible while another chooses $1,000.
A higher deductible can sometimes lower the premium because the policyholder agrees to take on more of the initial cost after a covered claim.
But choosing the highest deductible simply to reduce your monthly payment is not always a good idea.
Ask yourself one important question:
Could I comfortably pay this deductible tomorrow if my vehicle were damaged?
If the answer is no, the lower premium may not be worth the additional financial pressure.
Previous Claims Can Affect Driver Profiles Differently
Claims history can also affect insurance pricing.
However, not every claim is the same.
The type of claim, severity of the loss, circumstances surrounding it, and how long ago it occurred can all matter.
Different insurance companies can also evaluate the same history differently.
This is another reason shopping around can be useful.
A driver should not assume that one insurer’s quote represents what every company will charge.
Insurance Companies Do Not All Price Risk the Same Way
This is one of the most important reasons rates vary.
Two insurance companies can receive almost identical information about you and still produce different prices.
Why?
Because insurers do not all use the exact same pricing model.
One company may be more competitive for your particular type of vehicle.
Another may price your age group more favorably.
Another may have stronger discounts for your household.
Another may be particularly competitive in your state.
This means there is no permanent cheapest insurance company for everyone.
If you want to compare companies based on your own preferences, our Best Car Insurance Companies Finder can help narrow the options.
Discounts Can Change the Final Price
Discounts can make a significant difference in some insurance comparisons.
Depending on the company and your eligibility, you may find discounts related to:
- Safe driving
- Multiple vehicles
- Home and auto bundling
- Good student performance
- Driver training
- Defensive driving courses
- Low mileage
- Vehicle safety equipment
- Automatic payments
- Paperless billing
- Usage-based driving programs
But do not assume every discount advertised by an insurer will apply to you.
Eligibility can depend on your age, state, driving profile, policy type, or other requirements.
When comparing quotes, ask which discounts are actually included.
A Cheaper Quote May Simply Have Less Coverage
Imagine receiving two quotes:
Company A: $110 per month
Company B: $145 per month
At first glance, Company A appears clearly cheaper.
But then you discover that Company A has lower liability limits, a higher deductible, and no rental reimbursement.
Company B provides stronger coverage.
Now the comparison is completely different.
This is why comparing only the final monthly price can lead to the wrong conclusion.
Make sure you compare similar coverage.
Otherwise, you are not really comparing prices. You are comparing different insurance products.
Why Your Neighbor May Pay Less Than You
It is common for drivers to become frustrated after hearing what someone else pays.
“My neighbor pays only $90 per month. Why am I paying $150?”
The problem is that you may not know everything about your neighbor's policy.
Their:
- Vehicle may be different
- Driving record may be different
- Mileage may be lower
- Deductible may be higher
- Coverage limits may be lower
- Discounts may be different
- Insurance history may be different
Even small differences can change the final quote.
Instead of trying to match someone else’s premium, focus on finding the best value for your own profile.
Why Your Own Rate Can Change Over Time
Your insurance rate is not necessarily permanent.
Even if you stay with the same company, your premium can change when circumstances change.
Examples include:
- Moving
- Buying another vehicle
- Adding a driver
- A young driver receiving a license
- An accident
- A traffic violation
- Changing annual mileage
- Retirement
- Changing coverage
- Changing deductible
- Losing or gaining discounts
The insurance market itself can also change over time.
That is why it can make sense to review your policy periodically instead of assuming that the company that worked best five years ago is still your best option today.
How to Compare Auto Insurance Rates Properly
A proper comparison is more than collecting three random prices.
Use the same information with each insurer.
Keep these items consistent:
Drivers
Include the same household drivers where required.
Vehicles
Use the exact same vehicles and correct vehicle information.
Mileage
Give each insurer the same realistic annual mileage.
Coverage Limits
Do not compare low liability limits with much higher limits.
Deductibles
Use the same collision and comprehensive deductibles.
Optional Coverage
Keep rental, roadside, and other optional protections consistent.
Once those details match, the price comparison becomes much more meaningful.
How to Potentially Lower Your Auto Insurance Rate
There is no guaranteed trick that lowers insurance for everyone.
However, there are several practical steps worth checking.
Compare More Than One Company
Different companies price the same driver differently.
Getting multiple quotes can reveal significant differences.
Maintain a Clean Driving Record
Safe driving can help protect both your safety and your insurance profile.
Review Your Mileage
If you now drive considerably less than before, make sure the mileage on your policy is accurate.
Check Available Discounts
Ask which discounts actually apply to your situation.
Review Your Deductible
A different deductible may change your premium, but choose one you could realistically afford.
Consider Bundling
If you also need homeowners, renters, or another type of insurance, compare the total cost of bundling.
Compare Before Buying Another Car
Get insurance estimates before buying a vehicle, especially if insurance cost matters to your budget.
Review Your Policy Regularly
Life changes. Your insurance should reflect your current situation rather than information that was accurate several years ago.
Why the Cheapest Company Is Different for Everyone
This is the main lesson to remember.
There is no single company that is automatically cheapest for every driver.
A company might be inexpensive for:
- A 40-year-old driver with a clean record
but expensive for:
- A 19-year-old student
Another company might work well for:
- A retired low-mileage driver
but not for:
- Someone commuting 25,000 miles each year
Location can change the result again.
Vehicle choice can change it again.
Coverage can change it again.
That is why a personalized comparison is much more useful than simply asking which company has the lowest national average.
You can use our Best Car Insurance Companies Finder or browse our other insurance calculators to compare options for different types of drivers.
Frequently Asked Questions
Why is my car insurance higher than someone else's?
Your premium can be different because your driving history, vehicle, location, mileage, coverage, deductible, discounts, and other rating factors may be different.
Why do insurance companies give me different quotes?
Each insurer has its own pricing approach and may evaluate the same driver profile differently. That is why shopping around can produce different results.
Does my car affect my insurance rate?
Yes. Vehicle value, repair costs, safety features, theft risk, performance, and other vehicle characteristics can influence insurance pricing.
Does where I live affect car insurance?
Yes. Insurance costs can vary by state and local area because traffic, accidents, theft, repair costs, claims, and state rules can differ.
Can driving fewer miles lower my insurance?
It may help with some insurers. Mileage and vehicle usage can be part of the pricing process, and some companies also offer low-mileage or usage-based programs.
Does a higher deductible lower car insurance?
A higher deductible can sometimes reduce the premium, but it also means you may have to pay more yourself after a covered claim.
Why did my car insurance increase even though I had no accident?
Insurance prices can change for many reasons besides your personal accident history. Location, repair costs, policy changes, discounts, vehicle information, insurer pricing, and other factors may also affect your rate.
Is the cheapest car insurance company the same for everyone?
No. The cheapest insurer can change depending on the driver, vehicle, state, city, coverage, and discounts.