Does Getting Auto Insurance Quotes Affect Credit Score?
Does getting auto insurance quotes affect your credit score? Learn whether insurance quotes use soft or hard credit checks, how credit-based insurance scores work, and whether comparing multiple insurers can hurt your credit.
Does Getting Auto Insurance Quotes Affect Credit Score?
You want to compare car insurance prices.
You find three or four insurance companies and start requesting quotes.
Then a thought stops you:
Does getting auto insurance quotes affect credit score?
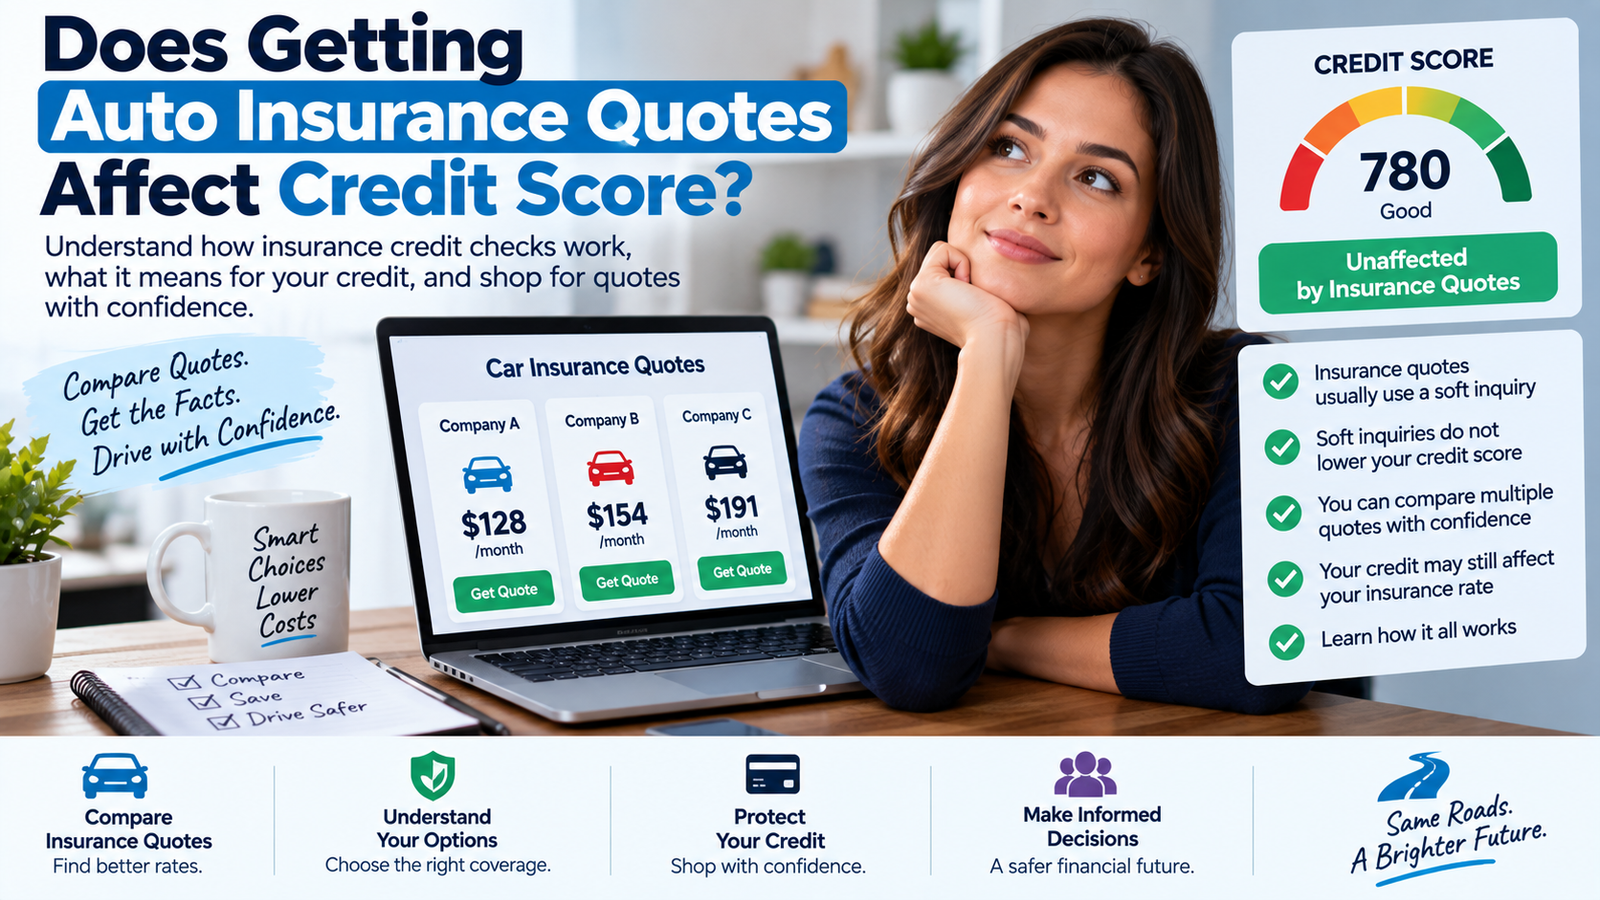
For most drivers, simply getting an auto insurance quote does not lower their credit score.
When an insurance company reviews credit-related information for an insurance quote, it is generally treated as a soft credit inquiry, not the type of hard inquiry normally associated with applying for a loan or credit card.
That distinction is important.
A soft inquiry can help an insurer review information used in its insurance-rating process, but the inquiry itself does not normally reduce your credit score.
So you generally do not need to avoid comparing auto insurance companies because you are afraid that every quote will damage your credit.
There is, however, another part of the story.
In places where it is permitted, information from your credit history may still influence an insurance company's pricing decision.
That means two separate things can be true at the same time:
Getting the insurance quote generally does not lower your credit score.
But credit-related information may still affect the insurance premium you are offered.
Understanding that difference makes the whole topic much easier.
What Happens When You Request an Auto Insurance Quote?
An insurance company needs information before it can estimate your premium.
You may be asked for details about:
- Your age
- Address
- Vehicle
- Driving history
- Annual mileage
- Previous insurance
- Household drivers
- Accidents
- Traffic violations
- Coverage limits
- Deductible
- Other information relevant to the policy
Depending on the insurer and the rules in your state, credit-related information may also be considered.
But you are not borrowing money when you request an insurance quote.
You are asking:
“How much might this company charge to insure me?”
That is very different from asking a bank:
“Will you lend me $30,000?”
This difference is why an insurance-related credit check is generally different from a credit check for an auto loan.
What Is a Soft Credit Check?
A soft credit check is a review of credit information that does not normally affect your credit score.
Soft inquiries can happen in several situations.
For example, you may encounter one when:
- Checking your own credit
- Receiving certain prequalified offers
- An existing financial company reviews an account
- An insurer checks permitted credit-related information
- Certain identity or account reviews take place
The important part for someone shopping for insurance is simple:
A soft inquiry does not normally take points away from your credit score.
This means you can generally request an auto insurance quote without treating it like a new credit application.
Please Also Check This...
What Is a Hard Credit Check?
A hard credit inquiry is different.
A hard inquiry commonly happens when you apply for a new form of credit.
Examples can include:
- Auto loans
- Credit cards
- Mortgages
- Personal loans
- Certain financing applications
Because you are asking to borrow money, the lender may perform a hard inquiry as part of the application.
A hard inquiry may have a small effect on a credit score.
That is why it is important not to confuse auto insurance shopping with auto loan shopping.
They may happen at almost the same time, especially when someone buys a new car, but they are different transactions.
Auto Insurance Quote vs Auto Loan Application
Imagine you are buying a car.
At the dealership, you apply for financing.
Later that evening, you start comparing auto insurance companies.
Both activities may involve credit-related information, but they do not necessarily affect your credit in the same way.
Auto Loan
You are asking a lender to give you money.
A hard credit inquiry may be involved.
Auto Insurance Quote
You are asking an insurance company for a policy price.
The credit-related check is generally a soft inquiry.
So if you recently purchased a vehicle and see a hard inquiry on your credit report, do not automatically assume your insurance quote caused it.
The financing application may be the reason.
Does Getting Multiple Auto Insurance Quotes Affect Your Credit Score?
Generally, requesting several auto insurance quotes does not reduce your credit score simply because several insurers looked at permitted credit-related information through soft inquiries.
This is important because comparing insurance companies can be useful.
Imagine these quotes for similar coverage:
Company A: $128 per month
Company B: $154 per month
Company C: $191 per month
Company D: $217 per month
That is a large difference.
Avoiding comparison shopping because you are worried about your credit score could mean continuing to pay considerably more than necessary.
You should still give every company accurate information and compare similar coverage.
But you generally do not need to limit yourself to one quote simply because you fear multiple insurance quote inquiries.
Why Do Insurance Companies Care About Credit?
This question often creates confusion.
An insurer is not deciding whether to lend you money.
Instead, where allowed, an insurance company may use certain credit-related information as one part of its process for estimating insurance risk.
Credit is not necessarily the only factor.
The insurer may also consider things such as:
- Driving history
- Claims history
- Vehicle
- Location
- Age or driving experience
- Mileage
- Coverage
- Deductible
- Household drivers
Two drivers can therefore have similar credit profiles and still receive very different insurance prices.
Credit Score and Insurance Score Are Not the Same Thing
Another common misunderstanding is assuming that the credit score shown by your bank is exactly what an insurance company uses.
That is not necessarily true.
Traditional Credit Score
A traditional credit score is mainly connected with lending decisions.
It can help a lender evaluate someone who is applying for credit.
Credit-Based Insurance Score
Where permitted, an insurer may use a credit-based insurance score or other credit-related insurance information as part of its insurance risk assessment.
Its purpose is different.
That means you should not assume:
“My banking app says my credit score is 720, so my insurance company must also be using 720.”
Insurance scoring and lending scoring are not necessarily the same system.
Can Your Credit Affect Your Auto Insurance Premium?
In some states, yes.
This is where people sometimes misunderstand the answer to the original question.
Suppose an insurance company performs a soft credit-related check.
That check itself does not normally lower your credit score.
However, information considered from your credit history may influence your insurance pricing where permitted.
So remember:
Credit check effect on your credit score: generally no effect when it is a soft inquiry.
Credit information effect on your insurance price: potentially yes, depending on state rules and insurer practices.
These are two completely separate issues.
Does Every State Allow Credit-Based Insurance Pricing?
No.
Insurance rules vary across the United States.
Some states restrict how insurers can use credit information, while others may place different conditions on its use.
That is why you should be careful with articles that make statements such as:
“Every insurer always uses your credit score.”
That is too broad.
Your location matters.
If credit-based insurance information is a concern for you, ask the insurer how it handles credit information in your state.
Will an Insurance Quote Appear on Your Credit Report?
A soft inquiry may appear in the section of your credit information that you can view yourself.
That does not mean it is damaging your credit score.
Seeing an insurance company's name associated with a soft inquiry should not automatically cause concern.
A soft inquiry and a hard inquiry do not have the same effect.
If you see an inquiry you do not recognize, however, it is sensible to investigate it.
Can You Ask an Insurance Company Whether It Checks Credit?
Yes.
There is nothing wrong with asking before completing a quote.
A simple question is enough:
“Does this quote involve a soft credit inquiry?”
You can also ask:
“Do you use credit-related insurance information in my state?”
Getting a clear answer can make the shopping process more comfortable.
Do You Need a Social Security Number for a Car Insurance Quote?
Not every company handles insurance quotes in exactly the same way.
Some insurers may be able to provide an initial estimate using information such as:
- Your name
- Address
- Date of birth
- Driver's license information
- Vehicle details
- Driving history
Another insurer may request additional identifying information.
If you do not want to provide certain information during an early quote, ask whether it is required.
Just remember that an initial estimate may change after the insurer verifies more complete information.
Does Buying Auto Insurance Hurt Your Credit Score?
Simply purchasing an auto insurance policy does not normally work like applying for a new loan.
Buying insurance and borrowing money are different activities.
However, there may be separate financial products connected with a vehicle purchase.
For example:
You buy a car.
You finance $25,000.
You buy auto insurance.
The financing application may involve a hard inquiry.
The insurance quote generally involves a soft inquiry.
Do not combine the two when trying to understand changes in your credit report.
What If You Have Poor Credit?
Having weaker credit does not automatically mean you cannot obtain auto insurance.
However, where credit-related insurance scoring is permitted, your credit history may be one factor considered in pricing.
Other information will still matter too.
For example:
- Your driving record
- Your state
- Your vehicle
- Your mileage
- Your coverage
- Your age
- Your accident history
- Your insurer
If one company gives you an expensive quote, that does not necessarily mean every company will charge the same amount.
Insurance companies can evaluate risk differently.
This is why comparing several insurers can still be useful.
You can use our Best Car Insurance Companies Finder to explore companies based on your own insurance needs.
What If You Have Excellent Credit?
Excellent credit does not automatically guarantee cheap car insurance either.
Imagine a driver with strong credit who also has:
- Two recent accidents
- Several traffic tickets
- A high-performance vehicle
- High annual mileage
- High coverage limits
That driver could still receive an expensive quote.
Insurance pricing usually considers a combination of factors.
Credit should never be treated as the only explanation for your premium.
What If You Have No Credit History?
Some people have little or no established credit history.
This can include:
- Young adults
- Recent immigrants
- People who avoid borrowing
- People who have not used traditional credit products
That does not automatically mean they cannot purchase auto insurance.
Insurers can consider many other factors.
If one company's price is high, compare alternatives before assuming the problem is the same everywhere.
For a price-focused comparison, you can also use our Top 10 Cheapest Car Insurance Companies tool.
Should You Check Your Own Credit Before Shopping for Insurance?
You can.
Checking your own credit is generally a soft inquiry and does not lower your score.
It can also help you identify possible errors.
For example, look for:
- Accounts that are not yours
- Incorrect payment history
- Wrong balances
- Duplicate accounts
- Incorrect personal details
If there is inaccurate information on your credit report, you may want to address it.
Keeping your financial records accurate is useful regardless of whether you are currently shopping for insurance.
Can Comparing Insurance Quotes Actually Save Money?
It can.
Insurance companies do not all calculate rates in exactly the same way.
One company may be competitive for a driver with a clean record.
Another may be more attractive for a household with several vehicles.
Another may offer better pricing for a particular state or type of driver.
That means comparing several quotes can reveal meaningful differences.
The goal is not simply to find the lowest number.
The goal is to compare the lowest price for similar coverage.
Compare the Same Coverage Every Time
Suppose you receive these two quotes:
Company A: $112 per month
Company B: $145 per month
Company A looks better.
But then you inspect the policies.
Company A has:
- Lower liability limits
- A $1,500 deductible
- No rental reimbursement
Company B has:
- Higher liability limits
- A $500 deductible
- Rental reimbursement
Now the comparison looks very different.
When requesting several quotes, keep these details as consistent as possible:
- Drivers
- Vehicles
- Liability limits
- Collision coverage
- Comprehensive coverage
- Deductibles
- Mileage
- Optional coverage
Otherwise, you may be comparing different products instead of different prices.
How Many Auto Insurance Quotes Should You Get?
There is no perfect number.
You do not need to contact every insurance company in America.
But one quote usually does not tell you much about the market.
A reasonable approach is to compare several companies that actually serve your location and driver profile.
You might include:
- Your current insurer
- Large national insurers
- Regional insurers available in your state
- Companies that fit your particular driver type
Because insurance quote checks are generally soft inquiries, you normally do not need to avoid reasonable comparison shopping because of credit-score concerns.
What Information Should You Prepare Before Getting Quotes?
Preparing your information first can make the process faster.
Have details available for:
Drivers
Names, ages, license information and relevant driving history.
Vehicles
Year, make, model and vehicle identification information where required.
Mileage
Use a realistic estimate of how much the vehicle is driven each year.
Current Coverage
Keep your current declarations or policy information available if possible.
Accidents and Tickets
Provide accurate information.
Coverage Preferences
Know whether you want minimum coverage, higher liability limits, collision, comprehensive or other options.
Using the same information with each company makes your comparison much more useful.
Can an Insurance Quote Change Later?
Yes.
An initial insurance quote is not always the final premium.
A quote may change if the insurer later discovers information that was missing or inaccurate.
For example:
You estimated your annual mileage incorrectly.
Another household driver needs to be included.
A traffic violation appears during verification.
The vehicle model was entered incorrectly.
A discount does not apply.
This is why accurate manual information is important when requesting quotes.
Do not intentionally hide information just to get a lower initial number.
Can Your Renewal Price Change Because of Credit?
Possibly, depending on the rules in your state and the insurer's practices.
But do not assume every renewal increase is caused by credit.
Your premium can also change because of:
- Accidents
- Tickets
- Claims
- Vehicle changes
- Moving
- Mileage
- Coverage changes
- Discount changes
- Repair costs
- Insurance market conditions
If your premium increases, ask what changed.
Understanding the reason is much more useful than guessing.
Does Paying Auto Insurance Build Credit?
Standard auto insurance is not the same thing as a credit account.
You should not expect ordinary insurance premium payments to work exactly like regular credit-card or loan payments.
You should still pay your premium on time.
Missing insurance payments can create other serious problems, including policy cancellation or a lapse in coverage.
If an unpaid balance eventually becomes a collection matter, that can create a different financial problem.
Why an Insurance Lapse Can Cost More Than You Expect
Trying to save money by allowing auto insurance to lapse can create problems beyond credit.
Depending on your circumstances, a lapse may leave you without required coverage.
It can also make future insurance shopping more difficult or expensive in some situations.
If you are struggling with a premium, contact the insurer before simply stopping payment.
Ask about:
- Payment options
- Coverage changes
- Discounts
- Deductibles
- Renewal options
And compare other insurers before allowing coverage to end unintentionally.
Should Credit Stop You From Shopping for Better Insurance?
Usually, no.
If you are paying too much, comparison shopping can be worthwhile.
The fact that insurers may use soft credit-related inquiries should not normally stop you from looking at alternatives.
Focus on the things you can control.
Use accurate information.
Compare the same coverage.
Check available discounts.
Review your driving record.
Review your mileage.
Check your deductible.
And look at several companies.
If you are unsure which insurers are worth comparing, use our Best Car Insurance Companies Finder.
How to Shop for Insurance Step by Step
Step 1: Review Your Current Policy
Write down your:
- Monthly or annual premium
- Liability limits
- Collision coverage
- Comprehensive coverage
- Deductibles
- Optional coverage
Step 2: Decide What Coverage You Actually Need
Do not reduce coverage simply to create a cheaper quote.
If you need help understanding policy protection, read What Does Auto Insurance Cover?
Step 3: Request Several Quotes
Use identical information where possible.
Step 4: Ask About the Credit Check
If you are concerned, confirm whether the insurer uses a soft inquiry.
Step 5: Review Discounts
Ask which discounts are actually included.
Step 6: Compare the Final Price
Do not compare only the first number displayed on a quote form.
Step 7: Compare the Policy
Make sure deductibles and coverage limits are similar.
Then decide which policy provides the better combination of cost and protection.
Frequently Asked Questions
Does getting auto insurance quotes affect credit score?
Generally, getting an auto insurance quote does not lower your credit score because the credit-related inquiry used for insurance is typically a soft inquiry.
Does getting multiple car insurance quotes hurt your credit?
Generally, no. Multiple insurance quote checks that are soft inquiries do not normally reduce your credit score.
Do car insurance companies check credit?
Some insurers may use credit-related insurance information where state rules permit it. Practices vary by insurer and location.
Is an insurance credit check hard or soft?
An auto insurance quote generally involves a soft credit inquiry rather than the hard inquiry commonly associated with borrowing money.
Does a soft credit inquiry lower your credit score?
No. A soft inquiry does not normally reduce your credit score.
Does an auto loan affect credit differently from auto insurance?
Yes. Applying for an auto loan may involve a hard inquiry because you are applying to borrow money. An insurance quote generally uses a soft inquiry.
Can my credit history affect my car insurance price?
It may where credit-based insurance information is permitted. However, many other factors can also affect your premium.
Is my insurance score the same as my normal credit score?
No. A credit-based insurance score serves a different purpose from a traditional lending credit score.
Can I request several insurance quotes safely?
From a credit-score perspective, insurance-related soft inquiries generally do not reduce your score. You should still provide accurate information to every insurer.
Should I choose the cheapest quote?
Not automatically. Compare coverage limits, deductibles, exclusions, discounts and policy features before choosing.
Does Getting Auto Insurance Quotes Affect Credit Score? The Bottom Line
So, does getting auto insurance quotes affect credit score?
For most drivers, the simple answer is:
Getting an auto insurance quote generally does not lower your credit score.
Insurance-related credit checks are typically soft inquiries.
That means comparing several auto insurance companies should not normally damage your credit simply because you requested quotes.
But remember the important distinction.
Where permitted, credit-related information may still influence the insurance premium an insurer offers you.
So:
The insurance quote itself generally does not hurt your credit score.
But:
Your credit history may still be one factor in insurance pricing where allowed.
Do not let confusion between these two ideas stop you from comparing your options.
Use the same driver details.
Use the same vehicle.
Use the same coverage.
Use the same deductibles.
Then compare several insurers.
For your next step, explore our Best Car Insurance Companies Finder, compare price-focused options with our Top 10 Cheapest Car Insurance Companies tool, or browse our Insurance Calculators for more personalized comparisons.