How Much Is Car Insurance Per Month? Average Cost in 2026
How much is car insurance per month? Learn the average monthly cost of car insurance in 2026 and see how coverage, age, location, vehicle, driving history, and discounts can affect your rate.
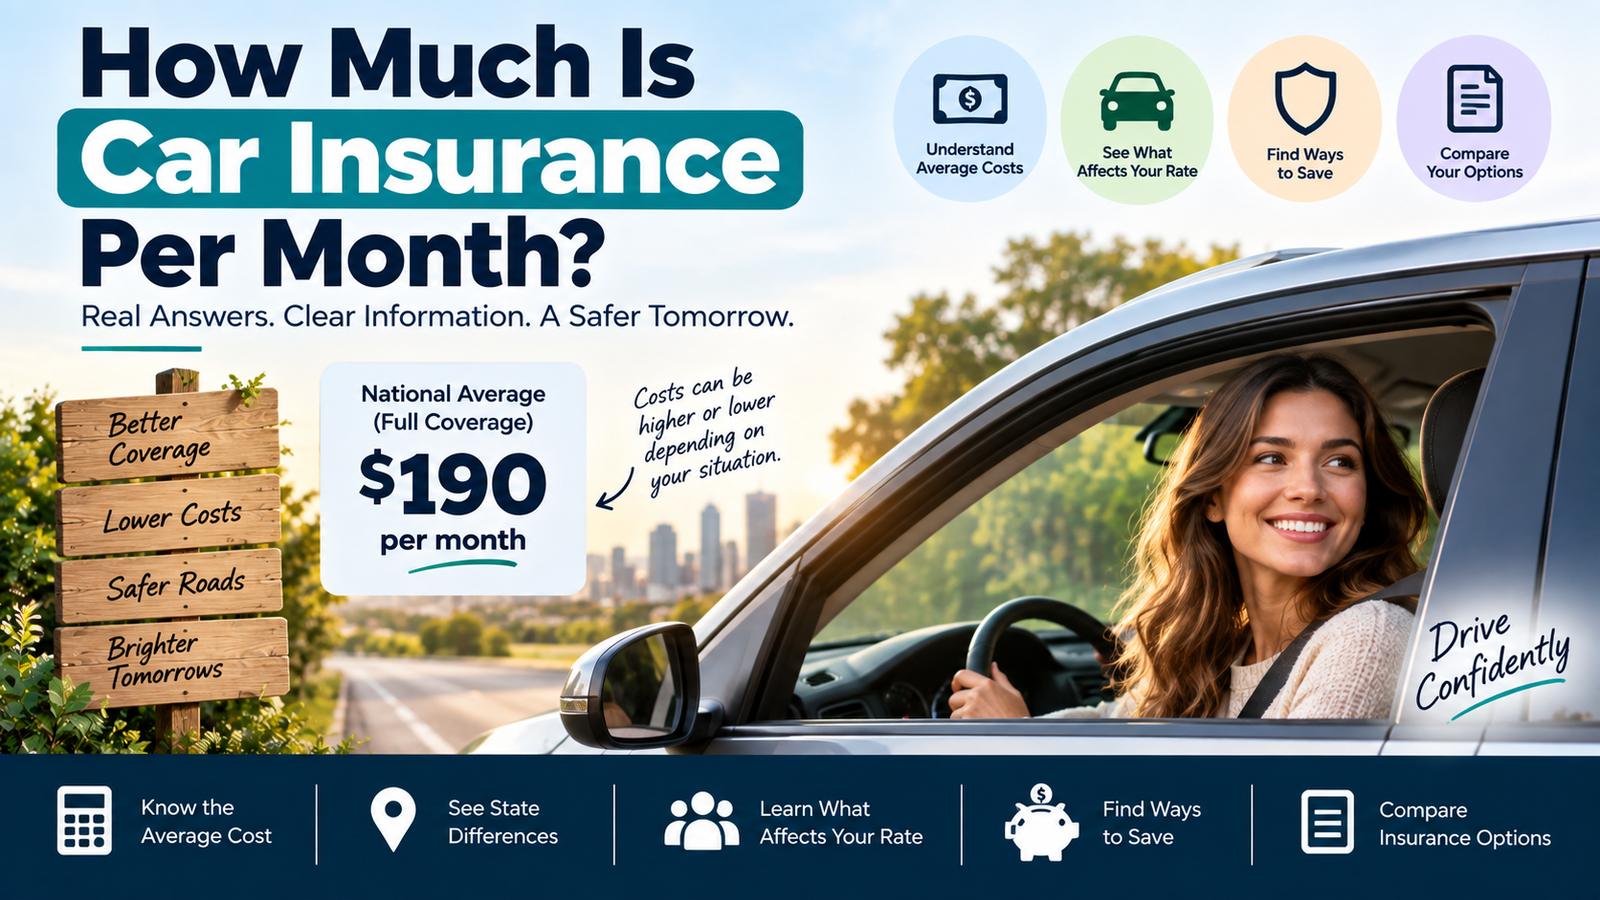
If you are wondering how much is car insurance per month, a useful starting point is around $190 per month for full coverage in the United States in 2026.
But that does not mean you will personally pay $190.
Some drivers may pay much less. Others may pay $250, $300, or several hundred dollars per month.
Drivers who buy only the coverage required by their state generally pay much less than drivers who buy full coverage.
Your actual monthly car insurance cost depends on many things, including where you live, your age, driving history, vehicle, coverage limits, deductible, annual mileage, and insurance company.
That is why the national average should be treated as a starting point rather than your expected bill.
Average Car Insurance Cost Per Month in 2026
For a simple idea of what drivers may see, think of car insurance in two broad groups.
Full Coverage
A national full-coverage policy costs roughly $190 per month on average in current 2026 estimates.
Full coverage normally combines liability insurance with collision and comprehensive coverage.
It usually costs more because the policy provides protection for more types of losses, including certain damage to your own vehicle.
Basic or Minimum Coverage
A policy closer to your state's minimum requirements can cost significantly less.
However, there is no single national price that applies everywhere.
State requirements are different, and the meaning of minimum coverage can also change depending on where you live.
A cheaper policy may save money each month, but it can also provide less financial protection.
Before choosing coverage only because it is inexpensive, make sure you understand what you are giving up.
If you are unsure about different types of coverage, read What Does Auto Insurance Cover?
Please Also Check Below....
https://bestcarandautoinsurance.com/why-auto-insurance-rates-vary
Why Your Monthly Car Insurance Cost May Be Different
Imagine two people who both own similar cars.
One pays $120 per month.
The other pays $230.
At first, that difference may seem strange.
But perhaps the first driver is 45 years old, has a clean driving record, drives 6,000 miles per year, and lives in a lower-cost area.
The second driver may be younger, drive 18,000 miles per year, live in a busy city, or have a recent accident.
Insurance companies do not look only at the car.
They look at a combination of factors.
That is why your personal quote matters much more than a national average.
Does Your State Affect Car Insurance Per Month?
Yes.
Where you live can make a major difference in your monthly car insurance cost.
Every state has its own insurance rules, required coverage, insurance market, claim patterns, and local risks.
A driver in one state may pay considerably more or less than a similar driver somewhere else.
This is also why searching only for the “average cost of car insurance in America” does not tell the whole story.
Your state is one of the first details you should consider when estimating your monthly payment.
Can Your City Affect Your Monthly Insurance Cost?
Yes.
Prices can sometimes vary even inside the same state.
A driver in a large city may have a different insurance rate from someone living in a smaller town.
Local conditions can include:
- Traffic
- Accident frequency
- Vehicle theft
- Vandalism
- Repair costs
- Local claims
- Weather-related risks
Even drivers who live relatively close to each other can receive different quotes.
This is why many of our Insurance Calculators ask for location information rather than using one national number for everyone.
How Age Can Affect Monthly Car Insurance
Age and driving experience can influence insurance pricing.
New and younger drivers often pay more because they have less experience behind the wheel.
That can make monthly car insurance particularly expensive for teenagers and drivers in their early twenties.
But age is not the only factor.
Two drivers who are both 20 years old can still receive very different quotes.
One may qualify for student discounts.
One may be on a family policy.
They may drive different vehicles.
They may live in different states.
Their driving records may also be different.
If you are comparing insurance for a younger driver, read Best Car Insurance for Young Drivers for a more focused comparison.
How Much Is Car Insurance Per Month for Young Drivers?
Young drivers often pay noticeably more than experienced adult drivers.
In some cases, the monthly price can be several hundred dollars.
There is no useful single number for every young driver because the result depends heavily on:
- Exact age
- State
- Vehicle
- Driving record
- Whether the driver joins a family policy
- Student status
- Coverage level
- Discounts
A teenager added to a parent's policy can have a very different cost from a young driver buying an individual policy.
The best approach is to compare personalized quotes.
How Much Is Car Insurance Per Month for Seniors?
Senior drivers can also see different rates as they get older.
However, many senior drivers have advantages that can affect their insurance situation.
For example, a retired driver may drive far fewer miles than someone commuting to work every day.
Some drivers may also qualify for mature-driver or defensive-driving programs.
For more information, see Best Car Insurance for Seniors.
Your Driving Record Can Change What You Pay
Your driving history is another important factor.
A driver with no recent accidents or major violations may receive a different rate from someone who has recently had an at-fault accident or speeding ticket.
The effect is not identical with every insurer.
One company may increase its price more than another.
That is one reason you should compare insurance companies rather than assuming your current rate is the only price available.
How Much Does Car Insurance Cost After an Accident?
There is no fixed monthly increase after an accident.
The result can depend on:
- Whether you were at fault
- The seriousness of the accident
- Your previous driving history
- Your state
- Your insurer
- Your coverage
- How recently the accident occurred
An accident may increase your premium, but different insurance companies can respond differently to the same driving history.
If your premium changes significantly, compare alternatives before your next renewal.
Can a Speeding Ticket Increase Your Monthly Cost?
It can.
A speeding ticket may change how an insurer evaluates your driving history.
However, not every ticket causes the same increase.
The speed involved, previous violations, state rules, and insurer can all matter.
This is another reason exact monthly costs are difficult to predict without a real quote.
The Vehicle You Drive Matters
Your monthly insurance cost does not depend only on you.
Your vehicle matters too.
Insurance companies may consider things such as:
- Vehicle value
- Repair costs
- Replacement parts
- Safety features
- Theft risk
- Vehicle performance
- Claim history for that type of vehicle
A basic family sedan may have a different insurance cost from an expensive luxury vehicle or high-performance sports car.
Before buying another vehicle, consider checking insurance quotes first.
You may discover that two similarly priced cars have very different insurance costs.
New Cars Can Cost More to Insure
Newer cars often contain expensive technology.
A modern bumper may contain cameras or sensors.
A headlight can cost much more to replace than it did on an older car.
Small accidents can therefore sometimes create expensive repairs.
However, newer vehicles may also contain safety equipment that insurers consider when pricing policies.
The relationship between vehicle age and insurance price is not always simple.
That is why you should request a quote for the exact vehicle you plan to insure.
Annual Mileage Can Affect the Cost
How often you drive may also matter.
Consider these two drivers:
Driver A drives 4,000 miles per year.
Driver B drives 22,000 miles per year.
They spend very different amounts of time on the road.
Some insurers consider annual mileage when calculating rates.
If you recently retired, started working from home, changed jobs, or reduced your commute, make sure your insurer has an accurate mileage estimate.
Coverage Level Has a Big Effect on Monthly Cost
One of the biggest reasons monthly insurance prices differ is coverage.
A policy that provides more protection generally costs more than a policy with less coverage.
For example, a driver may choose:
- State-required liability coverage
- Higher liability limits
- Collision coverage
- Comprehensive coverage
- Uninsured motorist coverage
- Underinsured motorist coverage
- Rental reimbursement
- Roadside assistance
Two people can therefore have very different monthly payments even if they use the same insurance company.
Always check what coverage is included before comparing prices.
What Is Full Coverage Car Insurance?
“Full coverage” is a common phrase rather than one single insurance product.
It generally refers to a policy containing liability coverage plus collision and comprehensive coverage.
Liability can help pay for covered injuries or property damage you cause to others.
Collision can help with certain damage to your own car after a collision.
Comprehensive can cover certain losses that are not collisions, such as theft or some weather-related damage.
The exact policy can contain additional coverage too.
Because more protection is included, full coverage generally costs more each month than a basic policy.
Do You Need Full Coverage?
Not every driver has the same needs.
If your vehicle is financed or leased, your lender may require collision and comprehensive coverage.
If you own an older car outright, you may have more flexibility.
But removing coverage only to reduce your monthly premium deserves careful thought.
Ask yourself:
How much would it cost to replace my car myself?
Could I afford that amount tomorrow?
The cheapest monthly policy can become expensive very quickly if it leaves you responsible for a loss you cannot comfortably pay.
Your Deductible Can Affect the Monthly Premium
A deductible is the amount you may have to pay yourself before certain coverage pays toward a covered claim.
For example, you might choose a $500 deductible or a $1,000 deductible.
A higher deductible can sometimes reduce the premium.
But that does not mean you should automatically choose the highest available deductible.
Ask yourself whether you could comfortably pay it after an unexpected accident.
Saving a few dollars per month may not be worthwhile if the deductible would create a financial problem later.
Does Credit Affect Car Insurance Cost?
In states where the practice is permitted, insurers may use credit-related insurance information as part of pricing.
Rules vary by state, and some states restrict this practice.
This is another example of why two people with similar cars and driving histories can still receive different insurance quotes.
Do Men and Women Pay Different Car Insurance Rates?
In some states and age groups, gender may be one of the factors used in auto insurance pricing.
However, the rules are not the same everywhere.
Gender also becomes only one part of a much larger pricing picture involving age, driving history, vehicle, coverage, location, and other factors.
The most useful number is still your personalized quote.
How Your Insurance Company Changes the Monthly Price
Perhaps the most overlooked factor is the insurer itself.
Insurance companies do not all price the same driver in exactly the same way.
You could provide the same information to several companies and receive several different prices.
One company might offer you $145 per month.
Another might quote $180.
Another might quote $230.
That does not necessarily mean one of them made a mistake.
They may simply evaluate your driver profile differently.
Use our Best Car Insurance Companies Finder if you want to compare companies based on your own preferences.
Is the Cheapest Company the Best Choice?
Not necessarily.
Price is important, but it should not be the only thing you compare.
Look at:
- Coverage
- Liability limits
- Deductibles
- Discounts
- Claims service
- Customer support
- Optional coverage
- Online tools
- Agent availability
A $120 policy is not automatically better than a $140 policy if the cheaper option gives you significantly less protection.
If price is your main concern, use our Top 10 Cheapest Car Insurance Companies tool as a starting point.
Can Discounts Reduce Your Monthly Car Insurance?
Possibly.
Discounts vary by insurance company and state.
Common examples may include:
- Multi-car discounts
- Home and auto bundling
- Good student discounts
- Safe-driver discounts
- Driver training
- Defensive driving
- Low-mileage programs
- Vehicle safety features
- Automatic payments
- Paperless billing
- Usage-based insurance
Ask the insurer which discounts are actually included in your quote.
Do not assume that every advertised discount applies to you.
Should You Pay Car Insurance Monthly or Annually?
Many insurers allow monthly payments.
This can make insurance easier to fit into a monthly budget.
Some drivers prefer paying the full policy premium at once when that option is available.
Before deciding, check whether your insurer charges installment or payment-related fees.
Compare the total amount you will pay during the policy period rather than looking only at the individual monthly payment.
Why Your Monthly Payment Can Change at Renewal
Your car insurance price is not permanent.
It can change at renewal even when you remain with the same company.
Your situation may have changed.
The insurer's pricing may also change.
Common reasons include:
- Moving
- Buying another vehicle
- Adding a driver
- Driving more or fewer miles
- An accident
- A traffic violation
- Changing coverage
- Changing a deductible
- Losing or gaining discounts
- Changes in local insurance costs
If your monthly price increases significantly, review your policy carefully.
Make sure all information is accurate and compare other companies if appropriate.
How to Lower Your Monthly Car Insurance Cost
There is no guaranteed method that works for everyone, but several steps are worth considering.
Compare Several Insurance Companies
This is one of the simplest things you can do.
Insurers can quote very different prices for the same driver.
Ask About Discounts
Make sure you know which discounts actually apply to you.
Keep Your Driving Record Clean
Safe driving can help you avoid accidents and violations that may affect insurance pricing.
Review Your Mileage
If you drive less than you used to, make sure your policy reflects your current usage.
Compare Before Buying a Car
Insurance costs can differ substantially between vehicles.
Review Your Deductible
A higher deductible may reduce the premium, but only choose an amount you could realistically afford.
Consider Bundling
If you also need homeowners or renters insurance, compare the total cost of keeping multiple policies with the same company.
Review Your Coverage
Make sure you are paying for coverage that fits your needs, but avoid reducing important protection only to create a lower monthly bill.
How Much Should You Personally Pay for Car Insurance?
There is no one correct monthly amount.
A good price for you depends on your own situation.
Instead of asking only:
“Is $150 per month cheap?”
Ask:
“What does this $150 policy actually cover?”
Then compare it with other quotes using the same:
- Driver information
- Vehicle
- Coverage limits
- Deductibles
- Mileage
- Optional coverage
That gives you a much more useful answer.
How to Compare Monthly Car Insurance Quotes Properly
Imagine these two quotes:
Company A: $125 per month
Company B: $155 per month
Company A looks cheaper.
But Company A may have a $1,500 deductible and lower liability limits.
Company B may have a $500 deductible and stronger coverage.
Those are not equal policies.
For a fair comparison, use similar coverage and deductibles with every insurer.
Then compare the price.
Frequently Asked Questions
How much is car insurance per month on average?
A useful 2026 national reference is around $190 per month for full coverage. Your personal cost may be substantially higher or lower depending on your location, driver profile, vehicle, and coverage.
Is $100 a month cheap for car insurance?
It can be, especially for full coverage, but price alone does not tell you whether a policy is good. Check the coverage limits, deductible, and protections included.
Can car insurance cost $50 per month?
Some drivers may find lower-coverage policies around this price range, but availability depends heavily on state, driver, insurer, and coverage.
Why is my car insurance $300 per month?
Possible reasons include your age, location, driving history, vehicle, coverage level, claims, mileage, or insurer. Young drivers and some higher-risk profiles can pay considerably more than national averages.
How much is full coverage car insurance per month?
Current national averages are roughly around $190 per month, but your personal quote can be very different.
Is minimum coverage cheaper than full coverage?
Usually yes because it provides less protection. However, state minimum requirements vary, and the cheapest policy may not provide enough protection for your needs.
Does my ZIP code affect my monthly insurance?
Location can affect insurance pricing. Drivers in different cities or areas may receive different rates even within the same state.
Does the type of car affect insurance?
Yes. Vehicle value, repair cost, theft risk, safety equipment, performance, and other characteristics may affect the premium.
Can I lower my car insurance by driving less?
Some insurers consider annual mileage and may offer low-mileage or usage-based options. Ask your insurer what is available in your state.
Should I switch companies if my premium increases?
Not automatically. First understand why the price changed and verify that your policy information is accurate. Then compare other companies using similar coverage.
How Much Is Car Insurance Per Month? The Bottom Line
So, how much is car insurance per month?
For full coverage, a reasonable national benchmark in 2026 is roughly $190 per month.
Basic or minimum-coverage policies can cost considerably less.
But your own number could be very different.
Your state, city, age, driving history, vehicle, annual mileage, coverage limits, deductible, discounts, and insurance company all matter.
Instead of trying to match a national average, focus on getting a good price for your own driver profile.
Compare several companies.
Use the same coverage when comparing quotes.
Check your deductibles.
Ask about discounts.
And most importantly, make sure the policy gives you enough protection rather than choosing it only because the monthly number looks low.